Independent advice on mergers, acquisitions, and capital info@lexford-capital.co
Lexford Capital Advisors
Contact

Mergers & acquisitions

Counsel to owners parting with a business and to the companies and investors acquiring one, delivered by senior bankers who remain with the transaction until it closes.

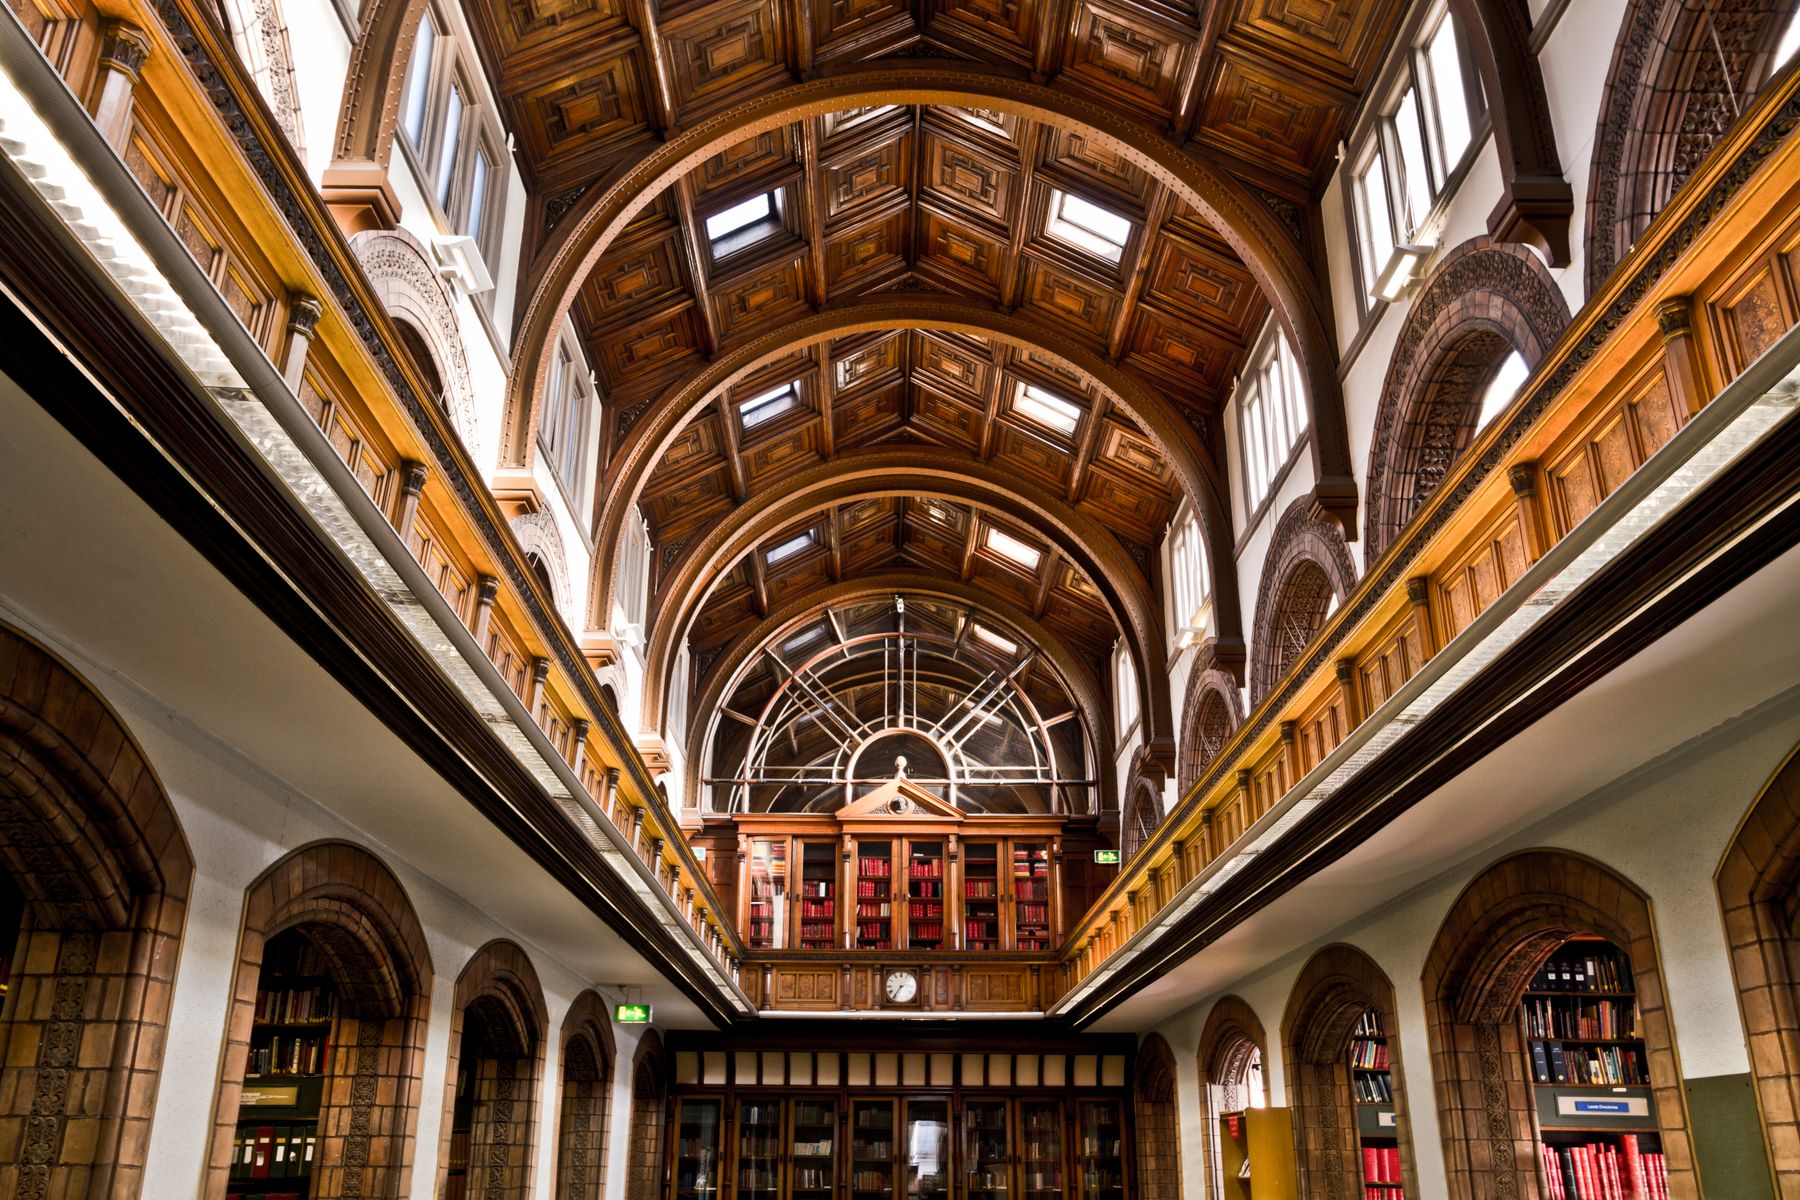
The vaulted reading room of a historic library with carved wooden galleries

One sale, conducted properly

For most proprietors, a company is sold only once in a lifetime. The terms they accept will settle their family’s financial security, the future of the people who helped build the business, and how the company is remembered in its community. A decision of that weight calls for more than an introduction to a single buyer.

In our experience the outcome is shaped long before an offer arrives. The quality of the financial information, the clarity with which the company’s story is told, the breadth of the buyer list, and the discipline of the negotiation each add to, or subtract from, the final result. We take responsibility for all four.

Our work begins with your objectives rather than a valuation. Some clients want the highest price; others care most about the buyer’s plans for their staff, about staying involved, or about closing by a certain date. Knowing your priorities lets us judge every offer against what you actually want.

When we act for acquirers, the same rigor runs in reverse. We help define the right target, reach owners who have not yet considered selling, and structure terms that protect the buyer long after the documents are signed.
Who we work with

Owners, families, and acquirers involved with established private companies.

Founders considering a sale

Your business is profitable and well established, and you want a buyer who will pay fairly and respect what you created.

Family shareholders

Relatives or several generations hold shares, and you need a fair, well-governed path to a sale or an internal transfer.

Strategic and financial acquirers

Acquisition is part of your strategy, and you want an experienced hand to locate, value, and secure the right business.

Our M&A services

Six kinds of mandate, each led by a senior banker from engagement to closing.

Sell-side representation

We prepare the company for market, identify the acquirers, both corporate and private equity, with a genuine reason to pay well, and run a timetabled process in which their offers are measured against one another. Nothing about your company is shared without your approval.

Suited to: owners who are ready to sell and want the best combination of price and terms.

Recapitalization

A private equity firm or family office buys a stake, often a majority, while you retain the rest. You take significant value off the table now and share in the gain when the investor eventually sells the company.

Suited to: proprietors seeking cash today and a capable partner, who expect the company to keep growing.

Acquisition search

We translate your strategy into acquisition criteria, research the companies that meet them, and make discreet first contact with their owners. We then lead valuation, structuring, and negotiation through to signing.

Suited to: companies and private equity sponsors seeking platform or add-on acquisitions.

Management buyout

Your leadership team acquires the business, financed with bank debt, a seller note, and sometimes a financial sponsor. We help set a fair price and a structure the company can comfortably support after closing.

Suited to: owners who want continuity for staff and customers, and teams ready to own what they run.

Generational transfer

Passing a company to children or relatives raises questions of fairness, financing, and control. We provide an independent valuation, design the funding, and help put sound governance in place before the transfer.

Suited to: family-owned businesses planning a handover over several years.

Divisional sales

Selling a subsidiary, product line, or business unit means separating staff, systems, contracts, and shared costs. We plan the separation in advance, so buyers see a clean business and the parent company is not disturbed.

Suited to: groups simplifying their portfolio or raising capital from a non-core unit.

The course of a sale

Most sales close six to nine months after we begin. Here is what happens along the way and where we will need your involvement.

  1. DiagnosisWeeks 1 to 4

    We review three years of financials, your customers and contracts, the management team, and conditions in your market, then share a frank view of value and of any issues a buyer is likely to raise.

    From you: several working sessions with us, and access to financial statements and tax returns.

  2. GroundworkWeeks 4 to 10

    We prepare the valuation model, draft the confidential memorandum, assemble the data room, and agree with you which buyers to contact and in what order to approach them.

    From you: review of our drafts, and the help of one or two trusted managers under confidentiality.

  3. OutreachMonths 3 to 5

    Buyers receive an anonymous profile first. Those who sign a non-disclosure agreement receive the memorandum, attend management presentations, and submit indications of interest.

    From you: time to meet serious buyers, with rehearsal and support from us beforehand.

  4. SelectionMonths 5 to 6

    We set competing offers side by side on value, structure, conditions, and certainty of closing, ask the leading bidders for their best terms, and settle a letter of intent that protects your position.

    From you: clear decisions on the points that matter most to you, such as price, earnouts, and your own role.

  5. ClosingMonths 6 to 9

    We manage confirmatory diligence, coordinate your lawyers and accountants, resolve issues as they arise, and keep both sides moving toward signing and the transfer of funds.

    From you: timely responses to requests, and continued focus on running the business well.

Our commitments

What every M&A client can rely on.

A senior lead

The person who first sits down with you leads the mandate personally, from kickoff to closing.

Straight answers

If the timing is wrong or the price would disappoint, we say so before you go to market.

Steady reporting

A written update after each milestone, covering buyer activity and next steps.

Aligned fees

The greater part of our fee is payable only when the transaction closes.

Questions from owners

What is a realistic timetable for a sale?

Six to nine months is typical from the start of preparation to closing. Companies with clean financials and a strong team can move faster, while complex ownership or regulatory approvals can add time. We give you a timetable at the outset and report against it.

How do you arrive at a value for my business?

We look at normalized earnings, growth, margins, customer concentration, and the prices paid for comparable companies, then consider which buyers could gain the most from owning yours. The result is a range, with a clear explanation of what would move it.

Can I sell only part of my company?

Yes. A recapitalization or minority sale lets you convert some of your ownership to cash while keeping a stake and, often, your role. Many owners take this route to diversify their wealth before a final exit later on.

How do you protect confidentiality?

Prospective buyers begin with an anonymous summary. Fuller information follows only once a confidentiality undertaking is in place, and the most sensitive data is held back until a preferred buyer has been chosen. We also help you plan when and how to tell employees.

What kinds of buyers will be interested?

Usually a blend of rivals in your own field, corporations looking to enter it, private equity sponsors, and family investment offices. Strategic buyers may pay for synergies, while financial buyers may offer more flexibility on your role. Inviting both usually produces the best result.

Will my staff be looked after?

A business is rarely bought without its people, and most acquirers know it. Retention plans, employment terms, and the buyer’s intentions can all be negotiated, and we make sure those questions are raised early rather than at the last minute.

How will taxes affect what I keep?

That depends on how the company is organized and how the transaction is structured, for example as a sale of shares or of assets. We bring your accountant and tax counsel in at the outset, so the structure is chosen with your after-tax result in mind.

What do your services cost an owner?

Our compensation is weighted heavily toward completion: a small engagement fee while the sale is prepared, then a percentage of the transaction value payable at closing. The arrangement is documented in full before we begin, and a first meeting is free of charge.

Begin with a confidential conversation

Write to us with a few lines about your business and what you are weighing. A senior advisor will answer personally, your message is held in strict confidence, and an initial discussion carries no fee or obligation.

info@lexford-capital.co